Independent claim appraisal · All 39 counties
Washington Insurance Appraiser: a second, independent number for your property claim
When your insurer accepts the claim but the check won’t cover the repair, Washington Insurance Appraiser builds a line-by-line valuation of the real cost and takes it through the appraisal process written into your policy.
- Your appointed appraiser
- Local pricing, county by county
- Homes, condos & commercial
- 39Washington counties served
- 12Appraisal & review services
- 7Free claim calculators
- 2 of 3Signatures make an award binding
What we do
What a Washington Insurance Appraiser does when a claim comes up short
Most underpaid claims in Washington aren’t denied. They’re trimmed. A roof gets two slopes instead of four. A soaked hallway is left out of the flooring line. A Douglas fir that cracked the rafters is treated as a shingle repair. Washington Insurance Appraiser exists for the gap between “covered” and “paid in full.”
We are appraisers, not adjusters or attorneys. Our job is one question: what does it really cost to put this property back the way it was? We answer it with our own inspection, our own measurements and pricing for your county.
- From scratch. We scope the loss ourselves. We never mark up the insurer’s estimate.
- Defensible. Every line is something we can support in front of an umpire.
- Honest triage. If you need an attorney or the OIC instead, we say so on the first call.
Washington weather
The losses a Washington Insurance Appraiser values most
Washington’s biggest claim events rarely look like the Gulf Coast’s. They come as wind, fire, ice and water.
 WindstormsPacific lows like the 1962 Columbus Day Storm and the 2024 bomb cyclone.
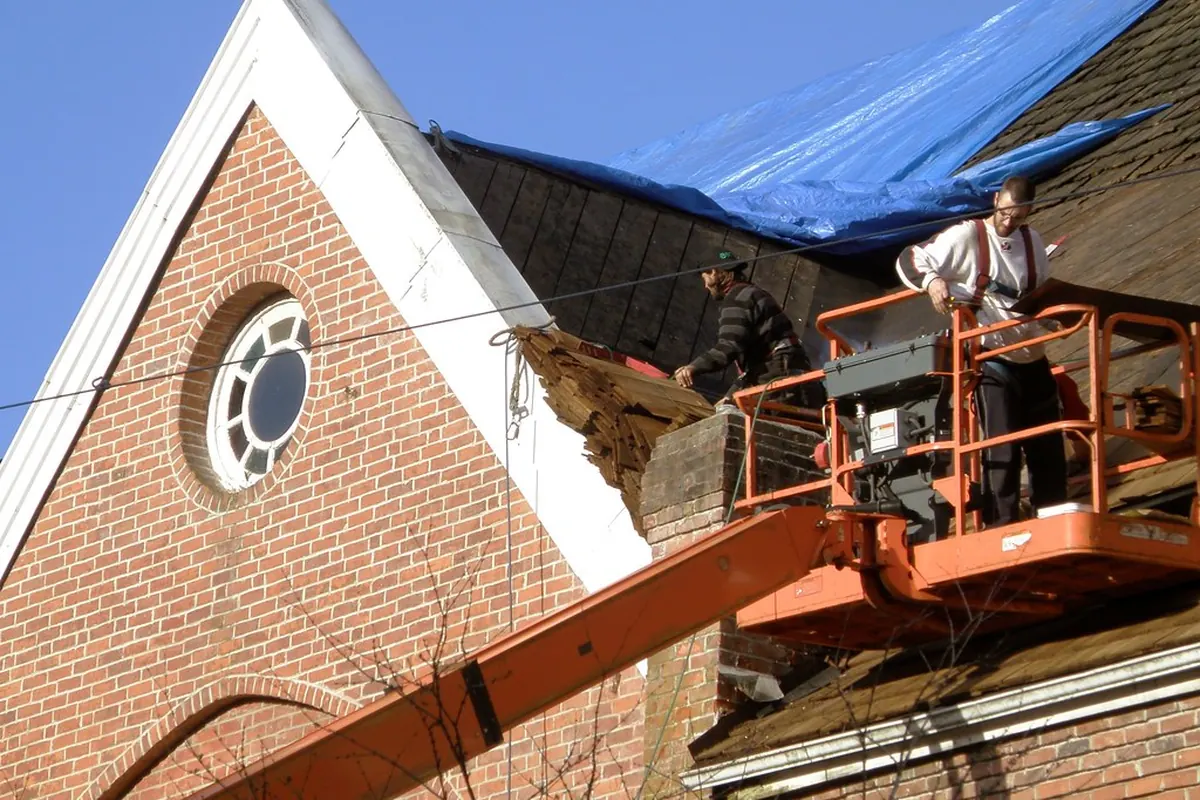
 Falling treesDouglas fir, cedar and bigleaf maple through roofs and framing.
 Wildfire & smokeTotal losses and ash-filled survivors, from Okanogan to Spokane County.
 Snow, ice & freezeIce dams, snow-load collapse and pipes that split in arctic blasts.
 Water & rainSupply-line failures and wind-driven rain during atmospheric rivers.
 Hail & roofsSummer storms east of the Cascades and roof disputes statewide.
 House fireStructure, smoke migration and contents losses room by room.
Appraisal services
Twelve ways Washington Insurance Appraiser can help with a disputed claim
Start with a review of the insurer’s estimate, or bring us in once appraisal has been demanded. Every service is built around one thing: a valuation that holds up.
 Service 01
Appraisal Clause Representation
We act as the appraiser you name once either side demands appraisal under your policy.Learn more Service 02
Homeowner Claim Appraisal
Single-family houses, townhomes and condo units where the carrier’s estimate misses real repair costs.Learn more Service 03
Condo, HOA & Commercial Appraisal
Master-policy, multifamily, retail, office and industrial losses with large scopes and long timelines.Learn moreService 04Roof & Hail Damage Appraisal
Shingle, metal, tile and low-slope roof disputes over slopes, repairability, steep charges and code items.Learn moreService 05Windstorm & Tornado Appraisal
Pacific windstorms, bomb cyclones and the occasional tornado: torn roofs, siding, fences and outbuildings.Learn moreService 06Fallen Tree Damage Appraisal
Douglas fir, cedar and maple impacts on roofs, framing and decks, plus removal and crane costs.Learn moreOne state, two climates
Westside and Eastside claims are not the same claim
The Cascade crest splits Washington into two very different places to own property. A Washington Insurance Appraiser has to price both.
Wet, windy and wooded
Mild, rainy winters punctuated by big Pacific windstorms. Tall evergreens come down on roofs, atmospheric rivers test every flashing detail, and rare arctic blasts freeze pipes in homes built for mild weather.
- Windstorms & fallen trees
- Rain intrusion & water losses
- Snow and ice events
- Condo and HOA losses
Dry, hot and snowy
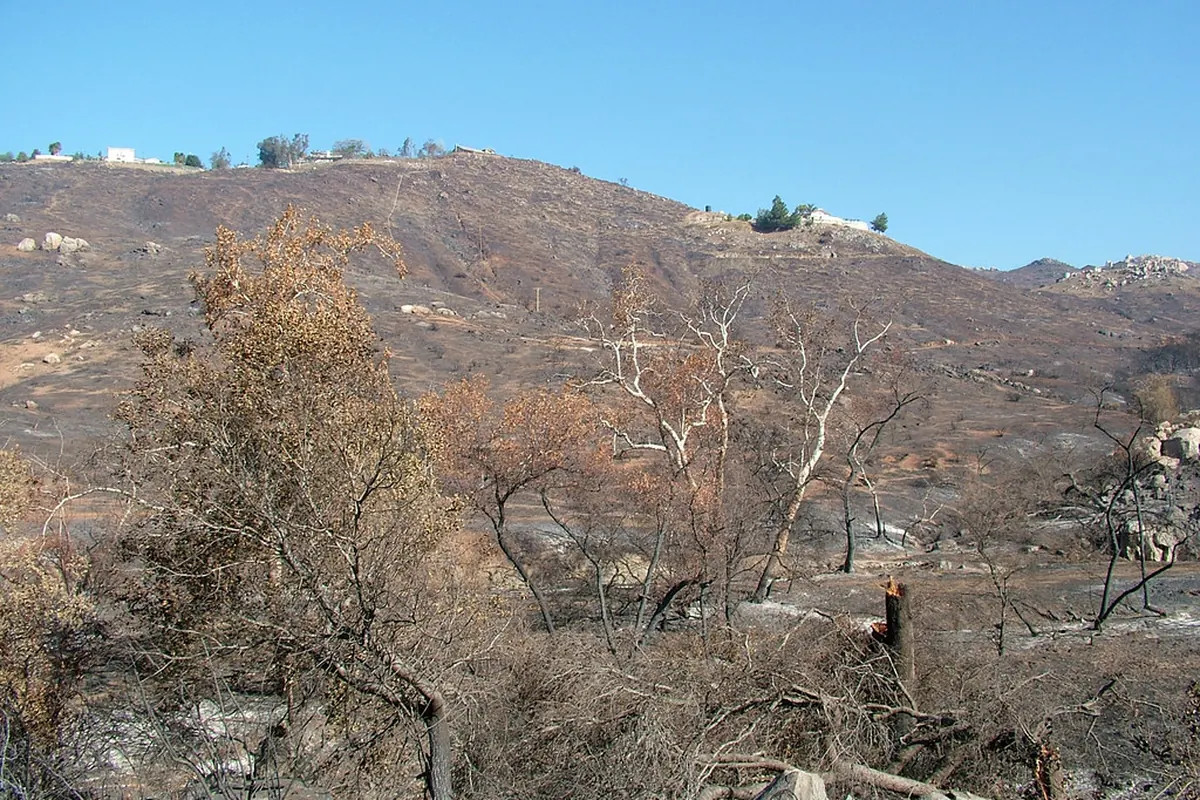
Hot, dry summers with thunderstorms, hail and wildfire, then cold, snowy winters. Ice storms in Spokane, heavy snow loads in Wenatchee and range fires around the Tri-Cities all show up in claims.
- Wildfire, smoke & ash
- Hail & summer wind
- Snow load & freeze
- Farm and commercial buildings
The process
How Washington Insurance Appraiser moves a stuck claim to a signed award
The appraisal clause turns an open-ended argument into a defined process with a binding result.
- 1
Put the disagreement on paper
Appraisal starts with a claim the insurer has accepted at least in part.
- 2
Send the written demand
If the gap remains, either side may demand appraisal in writing.
- 3
Each side names an appraiser
Each party picks a competent, independent appraiser, often within 20 days of the demand.
- 4
The appraisers choose an umpire
The two appraisers agree on a neutral umpire, ideally early so one is ready if needed.
- 5
The appraisers work the numbers
Most of the work happens here.
- 6
The umpire decides what’s left
Items the appraisers can’t settle go to the umpire.
- 7
The award is signed and paid
An award signed by any two of the three sets the amount of loss.
Quick gap check
Is your gap big enough for appraisal?
Type in the two numbers you already have. If the difference is large, a conversation with a Washington Insurance Appraiser makes sense. If it’s small, a documented supplement request may close it faster and for less.
The full appraisal payoff calculator adds appraiser and umpire fees so you can see a realistic net figure. Example numbers are illustrative.
See all 7 free calculatorsFree & private
Free claim calculators from Washington Insurance Appraiser
Run the numbers before you pick up the phone. Everything runs in your browser and nothing is stored or sent.
 Free calculator
Appraisal Payoff Calculator
See the disputed amount, a projected award and what you’d keep after appraiser and umpire fees.Open Free calculator
Replacement Cost Holdback Calculator
Estimate your first ACV check, the depreciation held back and the total once repairs are done.Open Free calculator
Roof Pitch & Squares Calculator
Turn a footprint into true roof squares using pitch and waste, then check the insurer’s figures.OpenFree calculatorPercentage Deductible Calculator
Turn a percentage earthquake, wind or hail deductible into dollars and see what a claim would pay.Open Free planner
Claim Timeline Planner
Map notice, proof of loss, depreciation and suit-limitation dates from your date of loss, then export them.OpenFree checklistAppraisal Readiness Quiz
Answer 12 yes-or-no questions to score your claim file and get a to-do list before you demand appraisal.OpenFree calculatorWildfire Total-Loss Coverage Check
Compare the real cost to rebuild after a wildfire with your dwelling, code and contents limits.OpenStatewide coverage
Cities where Washington Insurance Appraiser works most often
We serve all 39 counties. These local pages cover the communities where we handle claims most often.
Choosing a path
Appraisal, an OIC complaint or an attorney?
Each solves a different problem. Picking the right one first saves time and money, and Washington Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.
Appraisal
For when the insurer accepts coverage but you disagree on the amount. Two appraisers and an umpire set a binding number.
- Scope and price disputes
- Binding award on value
- Each side pays its appraiser
OIC complaint
For when the handling is the problem: delays, silence, unexplained decisions. The Office of the Insurance Commissioner asks the insurer to respond.
- Free to file
- Insurer must answer the regulator
- Not a lawsuit
Attorney & IFCA
For denials or conduct you believe was unreasonable. Washington’s Insurance Fair Conduct Act may provide remedies. Only a lawyer can advise you.
- Coverage denials
- Bad-faith concerns
- Notice rules apply
FAQ
Questions people ask Washington Insurance Appraiser
Straight answers about how appraisal works, what it costs and when it’s the wrong move.
What does a Washington Insurance Appraiser do?
A Washington Insurance Appraiser values property damage when you and your insurer agree the loss is covered but disagree about the cost. As your appointed appraiser we inspect, build an independent line-item estimate, work with the insurer’s appraiser and, if needed, present unresolved items to a neutral umpire.
How is an appraiser different from a public adjuster?
A public adjuster manages and negotiates the whole claim for you. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.
When should I call a Washington Insurance Appraiser?
When coverage is accepted, you have the insurer’s estimate, and the gap between it and your contractor’s number is meaningful, roughly more than 10% or several thousand dollars.
Is an appraisal award binding?
Yes, on the amount of loss, once any two of the three panel members sign it. That’s why documentation matters so much before you demand appraisal.
What does appraisal cost?
Each side pays its own appraiser and usually half the umpire. We put our fee in writing before any work starts, and the first conversation is free.
Do you cover my part of Washington?
Yes. We work in all 39 counties, with regular work around Seattle, Spokane, Tacoma, Vancouver, Bellevue, Everett, Olympia, Bellingham, Yakima, the Tri-Cities, Wenatchee and Bremerton.
Claim resources
Read this before you demand appraisal
Practical guides from Washington Insurance Appraiser on policy language, documentation and strategy.
Guide · 7 min readThe Appraisal Clause in Washington Policies: A Plain-English Guide
What the clause says, how a demand works and the limits of what a panel can decide.Read Guide · 6 min read
Appraisal, an OIC Complaint or an IFCA Claim: Which Path Fits?
Three ways to push back on a claim in Washington, and the problem each one is built to solve.Read Guide · 6 min read
How to Document Windstorm and Fallen Tree Damage
A practical checklist for the first days after a Pacific windstorm or a tree through the roof.Read
Before you sign off
The best time to check the insurer’s numbers is before you accept them
A short review now can save you from settling for a payment that won’t cover the repair.
Start with a conversation
Talk to Washington Insurance Appraiser about your claim
Tell us what happened and what the insurer offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing. No pressure, no obligation.
- Call or text+1 (844) 537-1427
- HoursMon–Fri, 8am–6pm Pacific
- CoverageAll 39 Washington counties